How can IT asset management support IT budgeting?
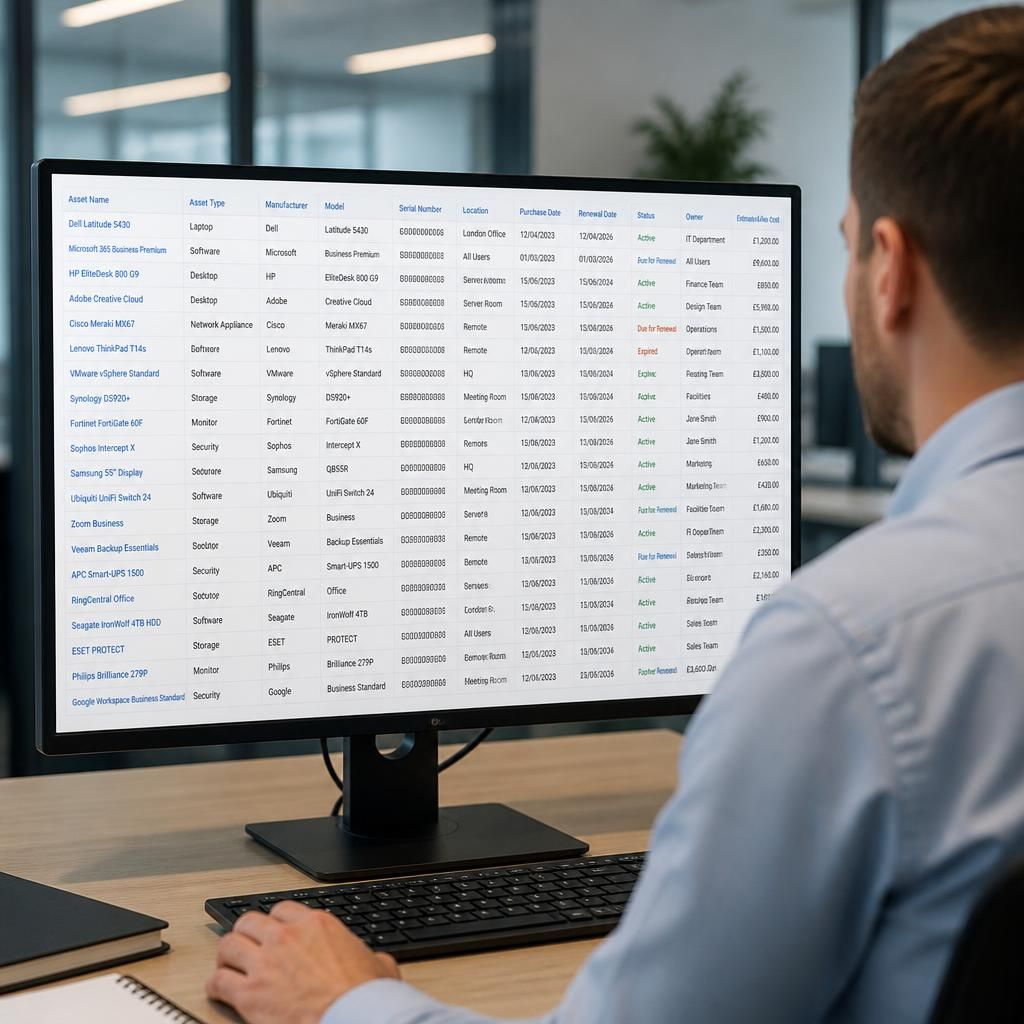
IT asset management supports IT budgeting by giving a business an accurate view of its hardware, software, users, contracts and renewal dates. This information helps budget owners forecast planned expenditure, identify avoidable costs and prioritise technology investments based on business needs and risk.
IT asset management supports IT budgeting by connecting technology decisions to the full cost and business purpose of each asset. Rather than treating IT spend as a collection of purchase requests, it gives budget owners a structured way to plan, approve, monitor and review expenditure throughout the asset lifecycle.
A useful budget process begins by separating different types of technology cost. An asset register can help distinguish capital purchases from recurring operational expenditure, such as subscriptions, support agreements, connectivity, hosting and maintenance. It can also show which costs relate to individual departments, sites or business functions. This makes it easier to prepare budgets that reflect how technology is actually used, rather than relying on broad historical allowances.
IT asset management can also improve total cost of ownership calculations. The purchase price of a laptop, server or network device is only one part of its financial impact. A more complete assessment may include deployment, configuration, licences, support, security controls, repairs, disposal and replacement. Including these elements helps a business compare options on their overall cost and suitability, not simply on the initial supplier quotation.
- Ownership costs: purchase, installation, configuration and disposal.
- Recurring costs: subscriptions, licences, warranties, maintenance and support.
- Operational costs: administration, security management, connectivity and user support.
- Replacement costs: planned renewal, migration, data transfer and staff familiarisation.
Asset information is particularly useful when creating a rolling replacement plan. Instead of replacing equipment only after it fails, a business can assess age, condition, compatibility, support status and operational importance. This allows likely expenditure to be distributed across future budget periods and gives decision-makers time to compare technical options. It also helps distinguish equipment that genuinely requires replacement from equipment that can remain in service with appropriate controls.
Budgeting should account for more than age alone. An older device may still be suitable for a low-risk role, while a newer asset may need attention if it is incompatible with required software, difficult to secure or unsuitable for a changing business process. IT asset management therefore supports a risk-based budget by linking proposed spending to factors such as business criticality, security exposure, resilience and compliance obligations.
Good records can also support scenario planning. A business may compare the financial and operational effects of:
- retaining existing equipment for longer;
- replacing assets in stages;
- standardising equipment to simplify support;
- moving a service to a cloud-based model; or
- increasing resilience for a critical system.
Each option can then be assessed against its ongoing cost, implementation requirements, operational dependencies and potential risk. This produces a more defensible budget discussion than selecting a solution solely because it has the lowest upfront price.
IT asset management can strengthen budget control after approval as well as during preparation. Comparing actual purchases and recurring charges with the approved plan can reveal unplanned additions, duplicate orders, unused services or costs assigned to the wrong department. Reviewing these variances helps refine future forecasts and makes it easier to identify whether additional spending resulted from a genuine business change, weak procurement control or incomplete records.
It can also improve accountability between finance, procurement, IT and department managers. Each group may need a different view of the same information: finance may focus on expenditure and commitments, procurement on supplier and contract decisions, IT on technical suitability, and department leaders on business value. A shared asset process gives these decisions a common evidence base while retaining the detail each stakeholder needs.
For the process to remain useful, asset data should be maintained as part of normal business activity. New purchases, transfers, disposals, changes in ownership and contract amendments should update the relevant records. Periodic reviews can then test whether the register reflects the working environment and whether budget assumptions remain valid. An outdated register can create false confidence, particularly where devices, users, licences or recurring services have changed.
In practice, an effective IT budgeting cycle uses asset management at several points: establish the current position, model future requirements, approve priorities, track expenditure and review the results. This approach does not remove the need for commercial judgement, but it gives business leaders clearer evidence for deciding what to fund, when to fund it and which costs should be challenged.
IT asset management supports budget governance by distinguishing committed technology costs from expenditure that still requires a business decision. This gives budget owners a clearer view of which amounts are contractually required and which can be reviewed, deferred or replaced.
For each relevant asset or service, records should identify the supplier agreement, renewal date, notice period, contract term, committed quantities and responsible budget owner. These details are particularly important for software subscriptions, support arrangements, connectivity services and hosted platforms, where failing to review an agreement before its decision point can limit the available options.
A practical process can classify planned expenditure as:
- Committed: costs already agreed under an active contract or purchase arrangement.
- Conditional: costs that depend on usage, growth, renewal or a change in business requirements.
- Discretionary: proposed investments that can be prioritised against other business needs.
This classification helps finance and IT focus their review on the right questions. A committed cost may need to be included in the baseline budget, while a conditional cost may require monitoring and a discretionary proposal should be assessed against its purpose, dependencies and risk. Asset management therefore adds useful structure to budget approvals without treating every technology cost as equally fixed.